All Categories
Featured
Table of Contents
Throughout this time, the Department of Education could renew your obligation to your loans if it's identified that you're no longer handicapped, your home earnings surpasses specific allowed limitations, or you take out new federal student loans. The Public Service Loan Forgiveness (PSLF) Program deals forgiveness for specific federal borrowers who work for qualified employers.
To get approved for federal student loan forgiveness, you should: Make 120 certifying payments toward your loansBe utilized by a U.S. federal, state, local, or tribal government, or a nonprofit organization Work full-time for that agency or organizationOwe qualified Direct Loans (or consolidate other federal loans into a Direct Loan) Register in an income-driven payment planIf you avoid payments throughout your loan grace period, while you're registered in school, or throughout certain deferment and forbearance periods, those won't count towards the 120 qualifying payments you need for loan forgiveness.

To get this benefit, you'll need to send a PSLF type licensing that you were employed with an eligible company or company for the period of the forbearance period. If you worked complete time for AmeriCorps or as a Peace Corps volunteer, you can count that time towards your qualifying service requirement.
There is no government financial obligation relief program for credit cards. Financial obligation relief companies offer services to assist you handle and pay off credit card financial obligation for less than you owe. When you settle credit card debt, you and the credit card company agree on a quantity you'll pay, which is less than the total balance you owe.
If you don't have a lump amount to offer your creditors (many individuals do not), you may choose to stop making credit card payments and rather set aside cash in a devoted account. If you stop paying your creditors for any factor, expect credit score damage and collection efforts. Insolvency has a major unfavorable effect on your credit score.
A disadvantage of choosing financial obligation settlement for debt relief is that it's likely to damage your credit standing. Keep in mind, nevertheless, that if you're currently falling behind on your payments, the chances are great you have actually already seen an unfavorable impact on your credit score.
If you're thinking about credit card financial obligation relief programs, research your options thoroughly. Check the services offered, the fees, and online evaluations to see what other people are stating. No matter which debt relief program you pick, the most essential thing is taking action to get your finances and credit back on track.
There might also be some downsides. It is very important to understand both the benefits and drawbacks. Debtors with government trainee loans may get approved for income-driven payment strategies. These plans can make a huge difference. They base your regular monthly payments on a percentage of your income. This assists ensure you can afford those payments.
Navigating 2026 Financial Relief Programs
Working enough time in certain public service professions might certify you to have the remainder of your debt forgiven. So could paying into an income-driven payment program for 20 or 25 years. Also, if you've ended up being completely and completely handicapped, you may not need to repay your student loans. Check for more details and to discover if you qualify.
Expert Analysis of 2026 Debt Management FrameworksFor example, student loan special needs discharge needs evidence of your condition. These programs are for people in authentic requirement, so not everybody will certify. In some cases, forgiven financial obligation is taxable income. Nevertheless, debt forgiven under federal student loan programs is normally an exception. There are a couple of states where forgiven federal trainee loan debt might be treated as taxable income.
Let's attend to some typical myths about government financial obligation relief programs to clear up any confusion. Reality: In a lot of cases, IRS and student loan financial obligation forgiveness programs are based upon your ability to pay. While they minimize the quantity you owe, they may not completely remove your debt. Truth: Various programs have various eligibility criteria.
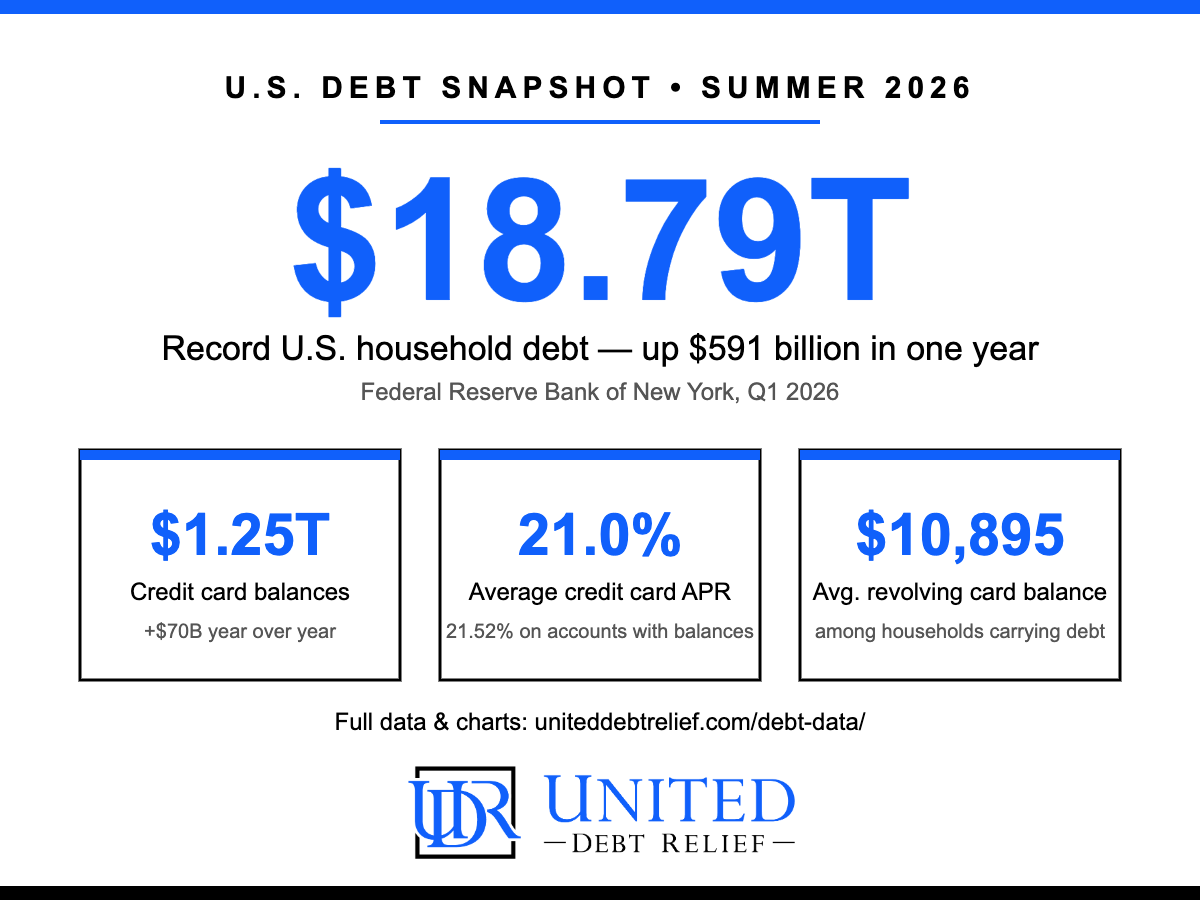
These programs are developed to help, not to add more tension. It deserves exploring your alternatives. Federal government financial obligation relief programs don't cover all kinds of financial obligation, but there are other options that can help. Private professionals and challenge programs can supply support and services. Here's what you can do if you have financial obligation problems the government can't fix.
Tackling Rising Consumer Debt in 2026
These companies include personal debt relief business and not-for-profit credit therapists. Here are a few of the solutions they may use: Hardship programs: Numerous lenders offer difficulty programs to assist you survive hard times. These programs might decrease or stop briefly payments, lower rates of interest, or waive fees for people experiencing financial trouble.
New 2026 Credit Relief Solutions for HouseholdsThis might lead to substantial debt reduction. Credit counseling: A licensed credit counselor can help you develop a spending plan and discover finance skills if you register in their debt management program. If you have debt problems, start taking steps to fix them: Connect to financial institutions to ask about hardship programsSpeak to a debt relief professional or credit counselor for a totally free consultationConsider which option best fits your situationAct quickly so you do not develop more debt or face collection actionsGovernment debt relief programs might be part of the option for you.
Countless Americans are fighting with credit card financial obligation, and in 2026, some may receive relief through credit card debt forgiveness programs. These efforts, used by significant charge card issuers and monetary organizations, are designed to assist eligible consumers decrease or get rid of exceptional balances under certain conditions. Eligibility for charge card debt forgiveness generally depends upon a number of crucial elements:: People experiencing considerable monetary challenges, such as task loss, medical emergency situations, or unanticipated home costs, might qualify.
Lenders may offer a settlement where a part of the debt is forgiven in exchange for a lump-sum payment or a structured payment plan.: Some programs require proactive engagement with the charge card issuer. Consumers may work with a financial therapist or directly with the creditor to negotiate a settlement quantity that is lower than the total balance owed.
Expert Debt Consolidation Reviews in 2026
This frequently needs careful budgeting to guarantee the settlement can be met in complete.-: Structured payment programs collaborated by credit counseling firms might include forgiveness clauses if the consumer effectively finishes the intend on time.-: Some companies provide short-term reductions in rate of interest, waived charges, or partial financial obligation forgiveness to account holders experiencing monetary difficulty.

Latest Posts
Eliminating Excessive Household Debt With 2026 Methods
Expert 2026 Debt Relief Solutions for Families
Objective Evaluations of Top Relief Strategies